





Directives relatives au calendrier de mise en conformité PT PMA 2026
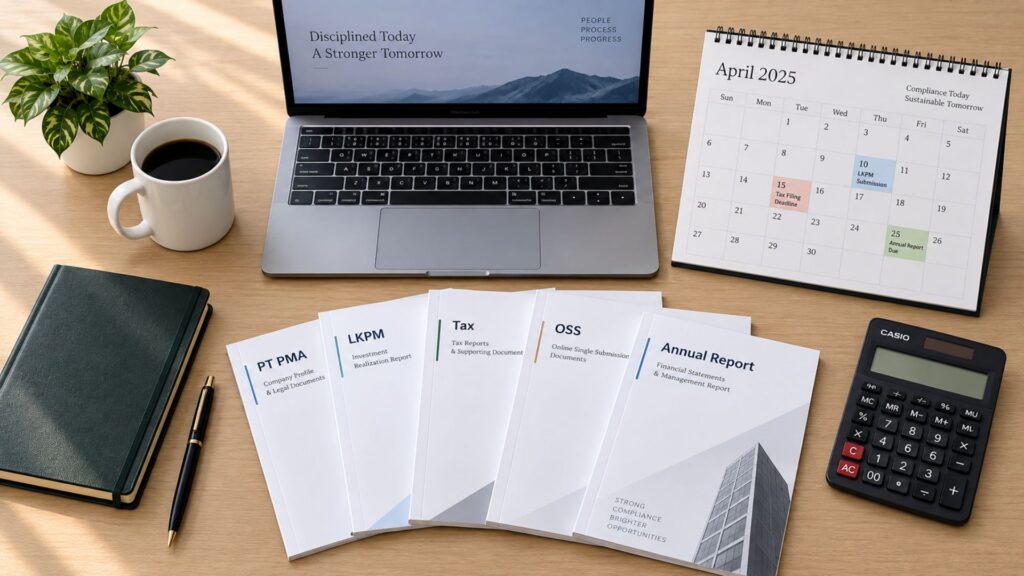
Setting up a PT PMA is only the start. Once the company is active, several compliance clocks begin to run at the same time.
Some duties repeat every month. Others come once a quarter or once a year. A few only appear when something changes, such as a new shareholder, a new business activity, or the first employee.
That is why a simple checklist is not enough. You need a calendar that tells you what is due, when to prepare it, and whether the rule applies to your company at all.
This guide gives you that calendar for 2026. It assumes your company uses a January to December financial year. If your financial year is different, some annual dates will also change.
What Changed for PT PMA Compliance in 2026?
LKPM deadline
Premièrement, current LKPM deadlines fall on the 15th after each quarter. Many older guides still show the 10th.
SABH filing clock
Second, Permenkum No. 49 of 2025 added the SABH annual-report approval submission, with a 30-day deadline from the notarial deed date.
PT PMA Compliance Calendar at a Glance
Use this section as your quick reference. The later sections explain what to prepare and when each duty applies.
Q4 2025 LKPM due.
Close the previous year’s books, reconcile payroll and tax records, and begin annual financial statements.
Continue closing annual accounts. Check whether a statutory audit may apply.
If you have employees, review payroll, BPJS, and manpower data.
Finalize records needed for the corporate annual tax return.
Compare legal data, OSS profile, shareholder records, and actual business activity.
Q1 LKPM due Apr 15.
Le 2025 corporate annual income tax return is generally due Apr 30 for a calendar-year company.
Prepare or finish the annual report for shareholders.
If an audit applies, make sure audited financial statements are ready for the annual corporate process.
For a calendar-year company, the 2025 annual report should generally be presented to the RUPS no later than Jun 30.
After approval, remember the separate 30-day SABH clock from the notarial deed date.
Q2 LKPM due.
Compare investment realization, workforce data, licenses, and OSS activities with actual operations.
Review sector-specific permits, operational licenses, and company records.
Do not assume every license has an annual renewal date.
Check whether company changes were recorded correctly across the relevant systems.
Review directors, commissioners, shareholders, address, capital, and business classifications.
Q3 LKPM due.
Fix data gaps between accounting records, OSS data, and investment reporting before year-end.
Start the year-end review early.
Reconcile tax accounts, major contracts, intercompany transactions, employee records, and supporting documents.
Prepare Q4 LKPM data, close open compliance items, and build next year’s calendar before the new reporting cycle starts.
Monthly Compliance: What May Repeat Every Month
Monthly duties depend on your activity, tax status, and workforce.
Employees
Do you have employees?
If yes, payroll can trigger employee income tax, BPJS contributions, and other manpower duties.
VAT / PKP
Are you registered as a PKP?
If yes, VAT reporting becomes part of your monthly routine.
Retenue à la source
Did you make payments that trigger withholding tax?
Services, rent, royalties, dividends, or cross-border transactions may create different withholding obligations.
Do not leave bookkeeping until April
Monthly bookkeeping is also important. Do not wait until April to rebuild a full year of records. A clean monthly close makes tax reporting, LKPM preparation, audits, and the annual report much easier.
Quarterly LKPM Reporting
LKPM stands for Laporan Kegiatan Penanaman Modal, or Investment Activity Report. It is one of the most important recurring reports for many PT PMA companies.
A PT PMA is categorized as a large business, so it generally submits LKPM quarterly, subject to specific exemptions.
| Quarter | Reporting period | 2026 / 2027 deadline |
|---|---|---|
| Q1 | January–March | Apr 15, 2026 |
| 2e trimestre | April–June | Jul 15, 2026 |
| T3 | July–September | Oct 15, 2026 |
| 4e trimestre | October–December | Jan 15, 2027 |
The report is filed through OSS. It can include investment realization, use of funds, employment, project progress, and problems affecting the investment.
Do not treat LKPM as a form you complete from memory on the last day. The figures should match the company’s real records.
Before each filing, compare the report with your accounting data, asset purchases, employee numbers, business location, project stage, and information already recorded in OSS.
If the company is still in the preparation or construction stage, the information you report may differ from an operating business. The reporting duty can remain, but the content should reflect the company’s actual stage.
April: The Busiest Compliance Month for Many PT PMAs
By April, the deadlines are already on your calendar. The real work is making sure the records behind them are ready.
If the company cannot complete the annual return on time, Indonesian tax rules allow a possible extension of up to two months when the required procedure is followed.
An extension does not mean you can ignore the filing until later. You still need to check the formal requirements, estimated tax position, and supporting documents.
This is why the best April preparation starts in January, not in the last week of the month.
Does Every PT PMA Need an Audit?
Non. PT PMA status alone does not automatically make every company subject to a statutory financial audit.
One important threshold
Under Indonesia’s Company Law, an audit is required in certain cases. One important threshold is when the company has assets or annual turnover of at least IDR 50 billion. Other categories can also require an audit, including certain public-interest companies and businesses covered by separate rules.
Check the company against the audit conditions before you build the annual reporting schedule. If an audit is required, start early enough for the audited statements to be ready before the RUPS process.
Annual Report and RUPS
The annual report is a corporate governance document, separate from the annual tax return.
The board of directors prepares the annual report and submits it to the RUPS after review by the board of commissioners.
Under the Company Law, this should happen no later than six months after the end of the financial year. For a company that closes its books on December 31, the practical outside date is Jun 30, 2026.
The annual report must include at least the required financial statements, information on the company’s activities and material issues, the board of commissioners’ supervision report, and other information required by the Company Law.
The exact content and approval process should match your company’s circumstances and articles of association.
New for 2026: Annual Report Approval Through SABH
Permenkum No. 49 of 2025 took effect on Dec 17, 2025. Under this rule, approval of the annual report must also be handled through Indonesia’s Legal Entity Administration System, known as SABH.
Because the deadline runs from the deed date, create the SABH task as soon as the deed is signed.
If the SABH filing is missed
If the company fails to comply, it can receive a written warning. If it still does not comply within 30 days after the warning notification, SABH access can be blocked.
July: Use LKPM as a Mid-Year Health Check
Q2 LKPM is more useful when you treat it as a review, not just a filing.
Before you submit it, compare the company’s OSS data with what has happened during the first half of the year.
These small mismatches are easier to fix when you find them early.
August and September: Review Licenses and Company Data
There is no universal PT PMA license renewal month, because timing depends on the license and business activity.
Your license review depends on the company’s KBLI classification, risk level, location, sector, products, environmental requirements, import activity, and other approvals.
Use August and September as a control period. Review what the company has changed since the start of the year.
October to December: Clean Up Before the Year Closes
Q3 LKPM falls in October, but the last quarter should also be used to prepare for the next annual cycle.
This reduces the risk of starting a new year with unfinished work from the old one.
Event-Based PT PMA Compliance
Some of the most important compliance duties do not sit on a fixed calendar at all. They begin when something happens.
Calendar 1: Fixed dates
Track monthly, quarterly, and annual deadlines that are known in advance.
Calendar 2: Business events
Track company changes that create a new filing, update, permit, or registration duty.
Which PT PMA Requirements Apply to Your Company?
All active companies should keep proper accounting and corporate records and meet the tax and corporate duties that apply to their status.
WLKP and Employment Reporting
If your PT PMA has employees, include WLKP, or Wajib Lapor Ketenagakerjaan Perusahaan, in the compliance calendar.
WLKP is generally required within 30 days after a company is established, reopened, or relocated, then annually. A company should also report no later than 30 days before relocation, closure, or dissolution.
Keep the reported workforce data consistent with the company’s real employee, payroll, and BPJS records.
BPJS Ketenagakerjaan Contributions
Companies with employees should also account for BPJS obligations.
Pour BPJS Ketenagakerjaan, employer contribution payments are generally due no later than the 15th of the following month.
The practical lesson is simple: payroll, BPJS, and employee tax should be reviewed together.
If one system shows a different number of employees, salary base, or employment status, fix the mismatch instead of carrying it forward month after month.
What Happens If You Miss a PT PMA Deadline?
The consequence depends on the obligation you missed.
Different obligations have different consequences
- A late tax filing can lead to tax penalties and follow-up from the tax authority.
- A missed or inaccurate LKPM can lead to administrative action under the investment supervision framework.
- Failure to complete the new SABH annual-report approval process can lead to a written warning and, if the issue continues, possible blocking of SABH access.
- Employment, BPJS, immigration, and sector-specific violations have their own rules and sanctions.
Do not assume that every late task creates the same penalty.
When a deadline is missed, first identify the regulator, the exact filing, and the legal basis. Then fix the outstanding item and document what was done.
How to Build a PT PMA Compliance System That Is Hard to Miss
PT PMA Compliance Checklist for 2026
Need Help Keeping Your PT PMA Compliant?
PT PMA compliance becomes difficult when one change touches several systems at once. The hard part is keeping the affected systems consistent after a company change.
Visa Indonesia can help you review the company’s current position, identify the filings that apply, and coordinate the next compliance steps.
The goal is not to give you a longer checklist. It is to help you keep the company records, licenses, and reporting duties aligned with how the business actually operates.
Foire aux questions
How often does a PT PMA submit LKPM in 2026?
A PT PMA is categorized as a large business, so it generally files LKPM quarterly through OSS, subject to specific exemptions.
What are the 2026 LKPM deadlines?
The deadlines fall on the 15th day after each quarter; see the calendar above for the 2026 dates.
Does every PT PMA need an annual audit?
No. PT PMA status alone does not require an audit; an audit applies when statutory or sector-specific conditions are met.
When is the PT PMA corporate tax return due?
Generally, it is due four months after the tax year ends. For a calendar-year company, that is normally the end of April.
When must a PT PMA hold its annual RUPS?
The annual report must be submitted to the RUPS within six months after the financial year ends.
What is the new SABH annual-report requirement?
Submit the notarized RUPS approval through SABH within 30 days after the deed is signed.
Does a PT PMA with no revenue still have compliance duties?
Yes. No revenue does not automatically remove corporate, tax, investment, or licensing duties. The exact filings depend on the company’s status, business stage, and registrations.
Does every PT PMA need BPJS and WLKP?
They become relevant when the company has employees and the applicable employment rules are triggered.
Prêt à demander ou à prolonger votre visa ?
Laissez nos spécialistes des visas s'occuper de votre demande.


Évolution des procédures d'obtention des permis de travail pour les travailleurs étrangers en Indonésie en 2026 : OSS, SIAPkerja et intégration à l'échelle nationale
En savoir plus
Comment faire une demande de visa d'exposition C11 pour l'Indonésie en ligne : guide étape par étape (2026)
En savoir plus
 English
 Bahasa Indonesia
 Español
 Italiano
 Français
 日本語
 Nederlands
 繁體中文
 한국어
 Norsk bokmål
 Svenska
 Dansk
 Türkçe
 Polski
 香港中文
 简体中文
 Українська
 Русский
 Bahasa Melayu